
Sezzle: Buy Now, Pay Later
- Rating
- 4.6
- Downloads
- 5.00M
- Content Rating
- Everyone
Sezzle: Buy Now, Pay Later - Screenshots
Pros
- Split purchases into four interest-free payments.
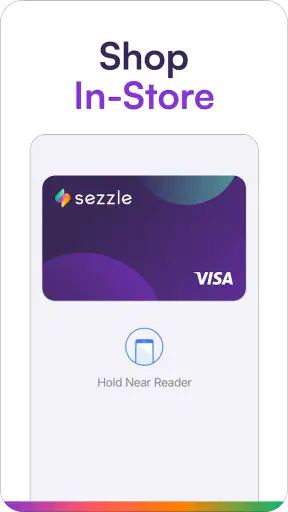
- Quick checkout at participating online and in-store retailers.
- No hard credit check for standard approval decisions.
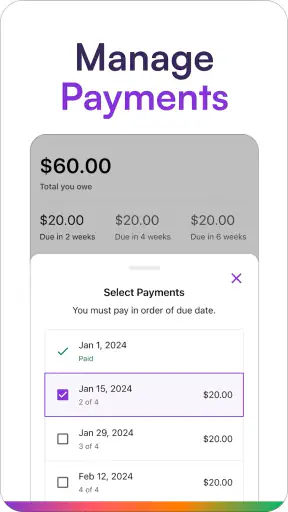
- Payment schedule is clearly shown in the app.
- Useful spending alerts help track upcoming installments.
Cons
- Late payments may lead to fees or account restrictions.
- Not every purchase or retailer is eligible for installment plans.
- A down payment may be required at checkout.
- Returned items can take time to update in your payment plan.
- Using multiple plans can make monthly expenses harder to manage.
Sezzle: Buy Now, Pay Later - Description
- App Name
- Sezzle: Buy Now, Pay Later
- Package Name
- com.sezzle.sezzlemobile
- Developer
- Sezzle Mobile
- Category
- Shopping
- Last Updated
- Mar 21, 2019
- Version
- 5.3.5
Sezzle is a shopping app from Sezzle Mobile that lets me divide an eligible purchase into scheduled interest-free payments instead of paying the full amount at checkout. I see it as a budgeting tool for planned purchases, not as extra money. That distinction matters: the app can make a payment easier to organize, but it does not make an expensive item cheaper or remove the need to keep enough money available for the later installments.
After spending time with it, I found the main experience straightforward once the account and checkout details are in order. The difficult moments are usually less about tapping the wrong button and more about understanding why an option is unavailable, why a payment needs attention, or why a retailer’s checkout does not behave as expected. My review focuses on those practical points, because they are what determine whether Sezzle feels useful or frustrating in everyday shopping.
Where the shopping experience can get stuck
The first place users may hesitate is at checkout. Sezzle’s central idea is simple, but the exact payment schedule, eligibility, and available choices can depend on the purchase and the checkout flow in front of you. The app’s store summary refers to splitting purchases into four or five interest-free payments, yet I would not treat that as a promise that every order will show both choices. The sensible approach is to read the schedule shown before confirming rather than assuming every purchase will be handled identically.
A second sticking point is confusing an approved-looking shopping flow with a completed order. I always check for confirmation from the retailer as well as confirmation inside the payment service. If the retailer’s page has not clearly accepted the order, I avoid immediately trying again. Repeating the attempt can create confusion about whether there are duplicate orders or temporary authorizations. Waiting briefly, checking the order area, and then checking the retailer’s own account is a safer workflow than pressing the purchase button several times.
Another common source of friction is a payment method that looks valid but cannot be used at that moment. An expired card, a changed billing address, a bank security block, or a card with insufficient available funds can interrupt a scheduled installment. I recommend treating the payment method as part of the setup, not as something to fix only after a problem appears. A little preparation makes the later payment dates much less stressful.
It is also easy to overlook the difference between a payment plan and a return. If I return an item, the retailer still has to process the return according to its own procedure. I would not assume that deleting an order from a shopping list, contacting the payment app alone, or simply refusing a card charge automatically completes that process. Keeping the retailer’s order details and return instructions nearby is especially useful for clothing, gifts, or anything ordered in multiple sizes.
For me, the most important mental check is this: an interest-free schedule is still a real financial commitment. The absence of interest does not remove the need to track future withdrawals. I would use the app for a purchase I can already afford over time, not to justify buying something that would be uncomfortable even when divided into installments.
What to check before creating a plan
I begin by checking the total cost, delivery charge, tax, and any optional extras at the retailer’s checkout. The amount that matters is the final amount, not the attractive price of the main item. I then look at the proposed installment dates and compare them with my normal income schedule. If the first payment is manageable but the later ones collide with rent, utilities, or another planned bill, I consider that a warning rather than a reason to proceed quickly.
I also check that I am signed into the intended account and that the email address used by the retailer matches the one I expect to use for payment records. Account mix-ups are easy to create when a phone stores several email addresses or when a household shares a device. Before confirming, I review the merchant name, order total, and payment method one more time.
The app is free to download, and its content rating is Everyone, which makes it broadly approachable. That does not mean every financial situation is suitable for it. Younger shoppers, shared-account users, and anyone relying on irregular income should involve the person responsible for the payment method and understand the schedule before placing an order. The friendly shopping interface should not disguise the seriousness of a scheduled charge.
Sezzle has been available since March 21, 2019, and its current version is 5.3.5. On Android, the listed minimum is version 7.0, so compatibility is worth checking before troubleshooting anything more complicated. If the app cannot install or behaves strangely on an older phone, I first confirm the operating system and available storage rather than assuming the account is at fault.
Small setup habits that prevent larger problems
My first useful habit is to keep notifications enabled for payment-related reminders if the phone’s settings allow it. I do not rely on a notification as the only record, but it gives me an extra prompt to review the account. I also keep a simple note or calendar entry with the order total, merchant, and scheduled dates. That is particularly helpful when several purchases are active at once.
My second habit is to use a payment method that I expect to remain active through the whole schedule. Moving money between accounts, replacing a card, or changing a billing address immediately after checkout can create avoidable work. If a card is close to expiring, I would rather resolve that before starting a plan than wait for a later installment to fail.
My third habit is to save the retailer’s confirmation separately. The payment app can help organize the financing side, while the retailer remains the important source for shipping, product changes, cancellations, and returns. Keeping both records prevents the common mistake of treating one service as if it controls the other.
These checks are not glamorous, but they reveal one of the app’s real trade-offs. Sezzle reduces the shock of a single full payment, yet it adds another layer to the purchase. I need to monitor both the shopping order and the payment schedule. For a single planned purchase, that extra layer is manageable. For many small purchases, it can become harder to remember than paying normally.
Recovering when a payment or checkout does not go smoothly
When a checkout stalls, I avoid changing several things at once. I first record what happened: whether the retailer showed an order number, whether the app displayed a plan, and whether any payment activity appears in the account. Then I close and reopen the relevant screens, check the internet connection, and try again only after I understand whether the first attempt completed. This simple sequence is safer than creating a second order while the first one is still processing.
If the app opens but a retailer’s checkout does not, I compare the same purchase in the retailer’s normal checkout and in the payment flow that offered Sezzle. This helps separate a retailer-page problem from an account problem. I also check whether the item, shipping destination, or final basket contents changed. A plan that was visible before an item was added may not remain available after the basket changes.
If a scheduled payment fails, I start with the basics: available funds, card status, billing details, and any security alert from the bank. I do not repeatedly submit the same payment without checking the account first. If the card is fine but the problem remains, I gather the order information, the affected installment, and the exact message shown before contacting support. Clear details make it easier to explain the issue than saying only that “the app is broken.”
For a missing order, I search the retailer’s email and account history before assuming the purchase vanished. I check spelling variations in the merchant name and look for a pending order rather than only a completed one. If there is no retailer confirmation and no clear plan record, I wait before attempting another checkout. If there is a retailer confirmation but the payment side looks incomplete, I keep both records and contact the service responsible for the specific part that is unclear.
Returns need the same careful separation. I follow the merchant’s return instructions first, retain tracking or confirmation details when applicable, and then watch the payment plan for the related adjustment. I would not cancel a payment simply because an item is on its way back unless the relevant service explicitly instructs me to do so. A return in transit and a completed refund are different stages.
One non-obvious advantage of this two-record approach is that it makes disputes easier to understand. The retailer can answer questions about fulfillment and merchandise, while Sezzle can answer questions about the scheduled payment arrangement. Treating every issue as a Sezzle issue wastes time; treating every issue as a retailer issue can leave the payment schedule unexplained.
When the phone, bank, or retailer is the real source of trouble
Not every error that appears while using the app originates in the app. A bank may decline a transaction for its own security reasons. A retailer may have a temporary checkout outage. A weak connection can interrupt a confirmation page even though the order is still being processed. On Android, an old operating system or a phone with very little free storage can also cause installation and performance problems. I check these surrounding factors before deleting the app or starting over.
Deleting and reinstalling can remove local friction, but I treat it as a later step, not the first response. Before doing it, I make sure I know the correct login details and have recorded any order information currently visible. Reinstallation cannot repair a bank decline, reverse a retailer cancellation, or change the terms of an existing payment plan. It may refresh the app, but it does not replace careful account checking.
I also avoid using an unfamiliar network for sensitive checkout if a trusted connection is available. This is less about Sezzle specifically and more about keeping the payment process predictable. If the same issue appears on a stable connection, with a current compatible phone and a valid payment method, I then have a clearer case for contacting support.
The app’s popularity suggests that many shoppers find this model practical: it has a 4.6 average from around 114 thousand ratings and more than 5 million installs. Those figures help explain why it is easy to encounter in modern shopping, but they do not predict whether a particular order will be approved or trouble-free. I use them as signs of adoption, not as a substitute for reading the terms shown on my own checkout screen.
Compared with paying by debit or credit card in full, Sezzle offers a clearer installment structure but requires more tracking. Compared with putting a purchase on a conventional credit card, the interest-free appeal can be attractive when the schedule is genuinely affordable, while a credit card may offer wider acceptance or a simpler single statement. Compared with saving first, Sezzle provides immediate access but removes the discipline of waiting. For nonessential purchases, saving remains the cleaner choice in my view.
Who benefits most, and who should skip it
I think Sezzle suits shoppers who have a planned purchase, predictable cash flow, and a strong habit of checking future commitments. It can be useful for spreading the cost of a necessary household item or a carefully budgeted seasonal purchase without turning the checkout into a large one-time withdrawal. The app is also convenient for people who prefer seeing an installment schedule rather than calculating dates manually.
I would be more cautious if income changes from week to week, if several buy-now-pay-later plans are already active, or if a person often forgets automatic payments. It is also a poor fit for someone who uses installment plans to make impulse purchases feel harmless. In those cases, paying in full, waiting and saving, or using a budgeting app without borrowing may be better.
A realistic example is replacing a broken appliance accessory when the full cost would interfere with this week’s grocery budget but the later payments are already covered by upcoming income. I would check the final checkout total, confirm every date, keep the retailer’s order email, and set a personal reminder. If the same person is also considering several unplanned clothing purchases, I would recommend pausing rather than stacking plans simply because each individual installment looks small.
The service is free, but “free” here describes access to the app rather than a guarantee that every possible situation carries no consequence. I read the payment details shown for the specific order and make sure I understand what happens if a scheduled charge cannot be collected. That habit is more important than the appeal of a zero-interest label.
My practical verdict after using it
Sezzle is best treated as a payment organizer, not a spending upgrade. Its strongest quality is clarity: when the checkout works and the schedule fits my budget, dividing a planned purchase into manageable payments is easy to understand. The app’s shopping focus, broad availability, and free entry make it approachable, and the Everyone rating reinforces that it is designed for a wide audience.
Its weakness is the extra responsibility around every order. I have to monitor the retailer, the payment method, the schedule, and the return process. A failed payment may involve the bank rather than the app, and a missing order may be a retailer issue rather than a financing issue. Users who expect one tap to solve every part of a purchase may find that separation frustrating.
For someone asking whether to try it, my answer is yes only when the purchase is already affordable and the dates fit comfortably. I would update the app, use a compatible device, verify the account and card details, and save both retailer and payment confirmations. If an issue appears, I would identify which side of the transaction is affected before retrying or contacting support.
Sezzle Mobile has built a useful option for shoppers who want scheduled payments without interest on the advertised installment arrangement. I would recommend it to organized users who value flexibility and are willing to keep track of commitments. I would skip it for impulse shopping, unstable finances, or any situation where paying in full or saving first would provide more control. Used with that discipline, it can make a planned purchase easier to manage; used casually, it can make a simple shopping decision harder to follow.
FAQ
What is Sezzle: Buy Now, Pay Later, and how does it work?
Sezzle is a buy now, pay later service that lets eligible shoppers split the cost of an online or in-store purchase into scheduled installments. During checkout, Sezzle generally shows the payment amount, due dates, and any applicable fees before you confirm. Approval is not guaranteed, and the exact terms can vary depending on your account, purchase, merchant, and payment history.
Does Sezzle check my credit, and can using it affect my credit score?
Sezzle may use different types of credit checks or account reviews depending on the product and circumstances. Some applications may involve a soft check, while certain longer-term financing options can have different requirements and may report payment activity to credit bureaus. Before accepting an offer, review the disclosures in the app carefully so you understand whether the plan could affect your credit.
Are there fees or interest charges when using Sezzle?
Many standard installment plans are advertised with no interest when payments are made on time, but fees may still apply in some situations. Possible charges can include late fees, rescheduling fees, payment processing costs, or interest on particular financing products. The amount depends on the plan and your location, so always check the final payment schedule and terms shown before completing a purchase.
What happens if I miss a Sezzle payment or need to change my payment date?
If a scheduled payment fails, Sezzle may retry the payment, restrict your ability to make new purchases, or charge a fee where permitted by the applicable terms. The app may offer payment-date changes or rescheduling options, but these are not always available and may involve a cost. Contact support promptly and update your payment method rather than ignoring a missed installment.
Is Sezzle safe to use, and what should I know about refunds or disputes?
Sezzle uses account security measures and payment authentication, but users should still protect their login details, enable available security features, and monitor account activity. Refunds are usually handled through the merchant first, while Sezzle adjusts the installment plan after receiving confirmation. A refund can take time to appear, and you may need to continue scheduled payments until the merchant processes it.


